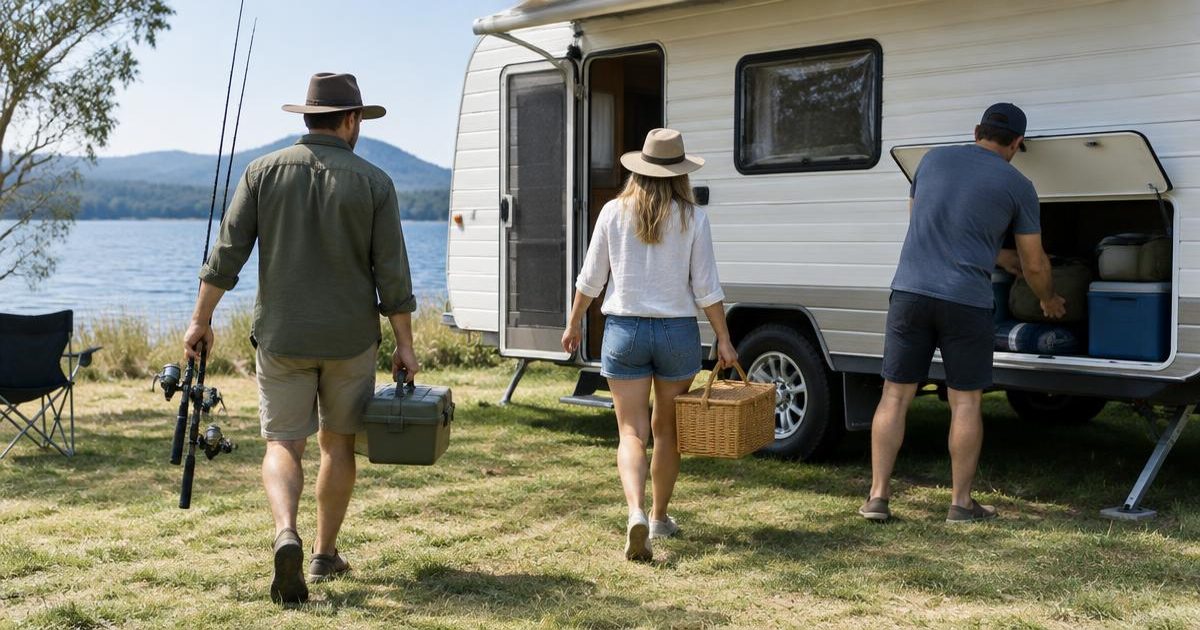
Sharing a caravan or boat with family or friends can spread ownership costs, but it also creates decisions that a solo buyer never faces. Who gets school holidays? Who pays after an accident? What happens when someone wants their money back? A practical written agreement can expose mismatched expectations before a deposit is paid. It should sit alongside suitable finance, insurance and legal arrangements, not replace them.
Agree on the asset and the purpose
Start with the kind of use everyone expects. Long touring trips, occasional weekends and frequent boating outings place different demands on an asset. Discuss where it will be stored, who can tow or operate it, and whether partners or other family members may use it.
Set a purchase budget that includes initial inspections, transfer costs, safety equipment and any essential upgrades. If one person wants a more expensive model, decide whether unequal contributions change ownership shares or simply create a separate amount owed. Record that distinction clearly rather than relying on memory.
Separate ownership from loan responsibility
Paying half the deposit does not necessarily mean the finance contract splits responsibility in half. Depending on the agreement, joint borrowers may each be responsible for the full debt. A private cost-sharing arrangement generally does not change a lender’s contractual rights.
Ask the lender whether the proposed ownership and borrowing structure is acceptable, including anyone who will not be a borrower. Understand how security over the asset works. A solicitor can help document ownership interests and responsibilities; the purchase receipt, registration and finance paperwork should not be assumed to answer every ownership question.
Create a booking system before arguments arise
Decide how bookings will work during peak periods and how far ahead each owner can reserve time. A shared calendar helps, but it needs rules for cancellations, late returns and trips that cross several weekends. Consider rotating first choice of popular holiday dates.
Also agree on handover standards. Fuel levels, cleaning, waste disposal, battery charging and reporting damage all affect the next person’s trip. Set an expectation that faults are reported promptly, even if they appear minor. Hidden damage can become a safety problem as well as a source of resentment.
- Allocate holiday periods and cancellation notice.
- Set rules for guests, pets and lending to others.
- Document collection, return and cleaning responsibilities.
Build a shared operating budget
Separate fixed ownership costs from trip-specific spending. Registration, insurance, storage and scheduled maintenance might be shared according to ownership, while fuel, campsite fees or marina charges may follow actual use. Agree how you will fund repairs that benefit everyone.
A dedicated record of contributions and spending reduces disputes. Set a process for approving major work and an amount someone can spend without seeking permission in an urgent situation. Budget for an insurance excess and unexpected repairs, rather than dividing only the predictable annual bills.
Check insurance and safe use
Tell the insurer about the ownership arrangement, all intended users, storage and planned activities. Ask whether occasional lending, different towing vehicles or particular cruising areas affect cover. Do not assume that a standard policy automatically suits shared ownership.
For a boat, confirm relevant licensing, registration, safety equipment and local operating requirements. For a caravan, check towing capacity, loaded weights and towing equipment for every vehicle that may be used. Agree who checks service dates and safety items, and stop using the asset if a significant fault needs investigation.
Plan an exit while everyone agrees
Write down what happens if an owner wants to leave, cannot pay, dies or becomes unable to use the asset. Consider a valuation method, a first opportunity for the other owner to buy, and a sale process if no agreement is reached.
Check how any outstanding loan would be paid out and how sale proceeds or a shortfall would be shared. A lender may need to approve changes to borrowers or security. Independent legal advice is particularly useful where contributions are unequal or the relationship makes difficult conversations easy to postpone.